Mind the Gap: Venture’s Feast or Famine Market


I started in VC in 2021, which was a strange time to learn the job. Rounds were moving quickly, valuations were stretching, and plenty of companies that looked highly fundable were also benefiting from a very forgiving market.
Since then, venture has reset. Investment has come back in parts of the market, but the number of companies getting funded has not.
A recovery, if you squint
European venture deal value grew for the second consecutive year in 2025, reaching €68.8 billion. Q1 2026 came in at €21.9 billion. On the surface, that looks like a recovery.
The problem is deal count. In Q1 2026, 2,805 European companies raised venture funding. At the 2021 peak, there were 15,459 deals across the year. So capital is coming back, but it is not spreading across the market in the same way.
Chart 1 – European VC Activity 2016 – Q1 2026

Venture has recovered for the companies everyone wants. The rest of the market looks very different.
The feast
For the strongest companies, conditions are competitive. Deals above €25 million now account for 79.2% of all European deal value, up from 68.8% in 2025. The same pattern is visible in the US. Data from SVB shows the top 1% of venture-backed companies by valuation now receive 33% of all venture dollars, up from 12% in 2022. The bottom half receive just 7%.
For the best companies, the market feels competitive again. For everyone else, the reset is still very much here.
Chart 2 – Capital concentration
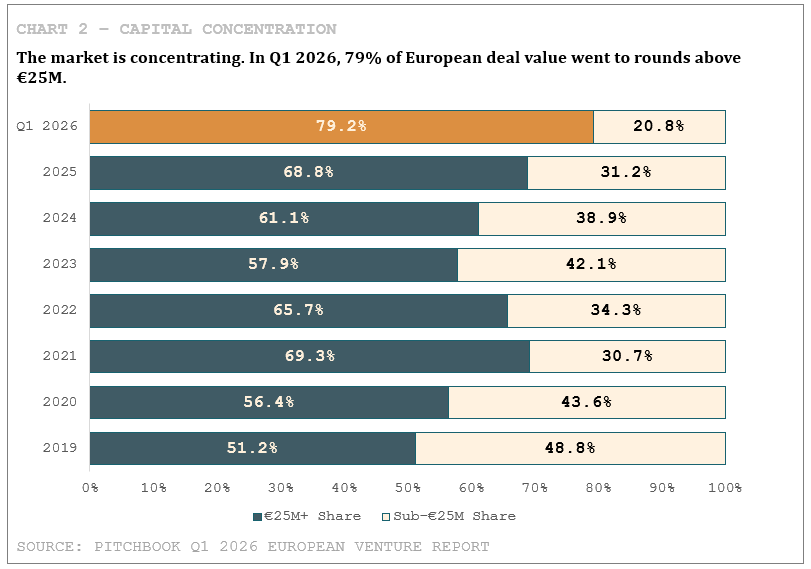
For the best companies, fundraising is still competitive. Strong teams with real traction in credible markets can still raise quickly and on strong terms. But the bar for being in that group has moved up.
This is the part that feels a bit familiar.
In 2021, rounds moved quickly, valuations stretched, and the bar to raise was much lower than it is today. Strong companies got funded, but so did plenty of weaker ones. The reset has probably been healthier for the market, even if it has been painful.
What is different now is how selective the market has become. Weaker companies are struggling to raise at all, and plenty of good companies are finding the next round harder than expected. But at the top end, some round sizes and valuations look familiar.
As someone who spends a lot of time valuing startups, that raises an obvious question: are the companies attracting this capital materially stronger than the 2021 cohort, or is the same optimism now being concentrated into fewer names?
Some will be exceptional, but not all of them.
Data from PitchBook shows the median TVPI for a 2021 vintage fund currently sits below cost. And according to the British Business Bank, UK funds suffered portfolio markdowns in 2022 and 2023, with pooled TVPI falling 7-9% annually. Although, the 2025 report shows this trend has now stabilised.
The famine
Outside that top band, the market looks very different. Series A activity in Europe is materially below its 2021 peak. At the same time, the bar to raise one has moved materially higher.
The result is a widening gap between what looked fundable in 2021 and what can actually graduate today.
The ARR bar for a Series A has moved up a lot since 2021. There is obviously no single threshold. Team, market, growth rate, efficiency and investor appetite all matter. But when you speak to founders and investors, the direction is pretty clear.
When I started in VC, a company at £1m ARR growing 100% year-on-year was a credible Series A candidate. Today, that can still be a good business, it just may not be a Series A business.
Point 9 SaaS funding napkin 2022
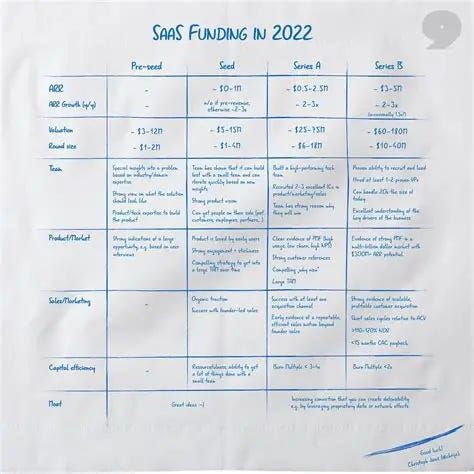
That same company today is having a harder conversation. Investors want more ARR, faster growth, and clearer evidence that the business can support the next round.
That is the gap and the companies caught in it are not necessarily failing. Many are good businesses, built to a standard that would probably have been fundable a few years ago.
The graduation crisis
Fewer companies are moving from one round to the next.
With capital more freely available, the seed cohorts from 2020 and 2021 were large. Those companies are now at the four-to-five year mark, but most have not raised a Series A.
Recent analysis from Peter Walker at Carta shows how sharply the market has changed. In 2020, roughly 35–40% of Seed companies were raising a Series A within two years. By H2 2021 that had started to fall, and by 2022 it was down to the mid-teens. No cohort has seen a 30% graduation rate or higher since Q3 2021.
European-specific data is harder to come by, but data from Atomico, Dealroom and Crunchbase shows the same direction. The share of European seed-stage companies raising a Series A within 12 months has fallen from roughly 10–13% in 2020–2021 to around 6% by H2 2024.
Part of the reason Series A rounds feel tighter is that the bar has moved on both sides.
Seed rounds are now bigger, more competitive, and often include investors who would typically have invested at Series A, with funds moving earlier to secure ownership in the best companies. That gives founders more runway, but it also means they are expected to prove more before raising again. Bigger Seed rounds buy more time, but they also move the Series A bar up.
AI has pushed the benchmark up too. A small number of AI-native companies are reaching meaningful revenue with very lean teams, which can make more traditional software companies look slower by comparison.
So the bar is not just higher because investors are more cautious. It is also higher because founders have more time to prove things at Seed, and because AI has changed the reference point for what fast growth can look like.
The pressure is not limited to seed. SVB notes that only 13% of US Series A companies raised a Series B within 24 months. Graduation has become harder across the funnel, not just in the very early rounds.
Chart 3 – Graduation rate
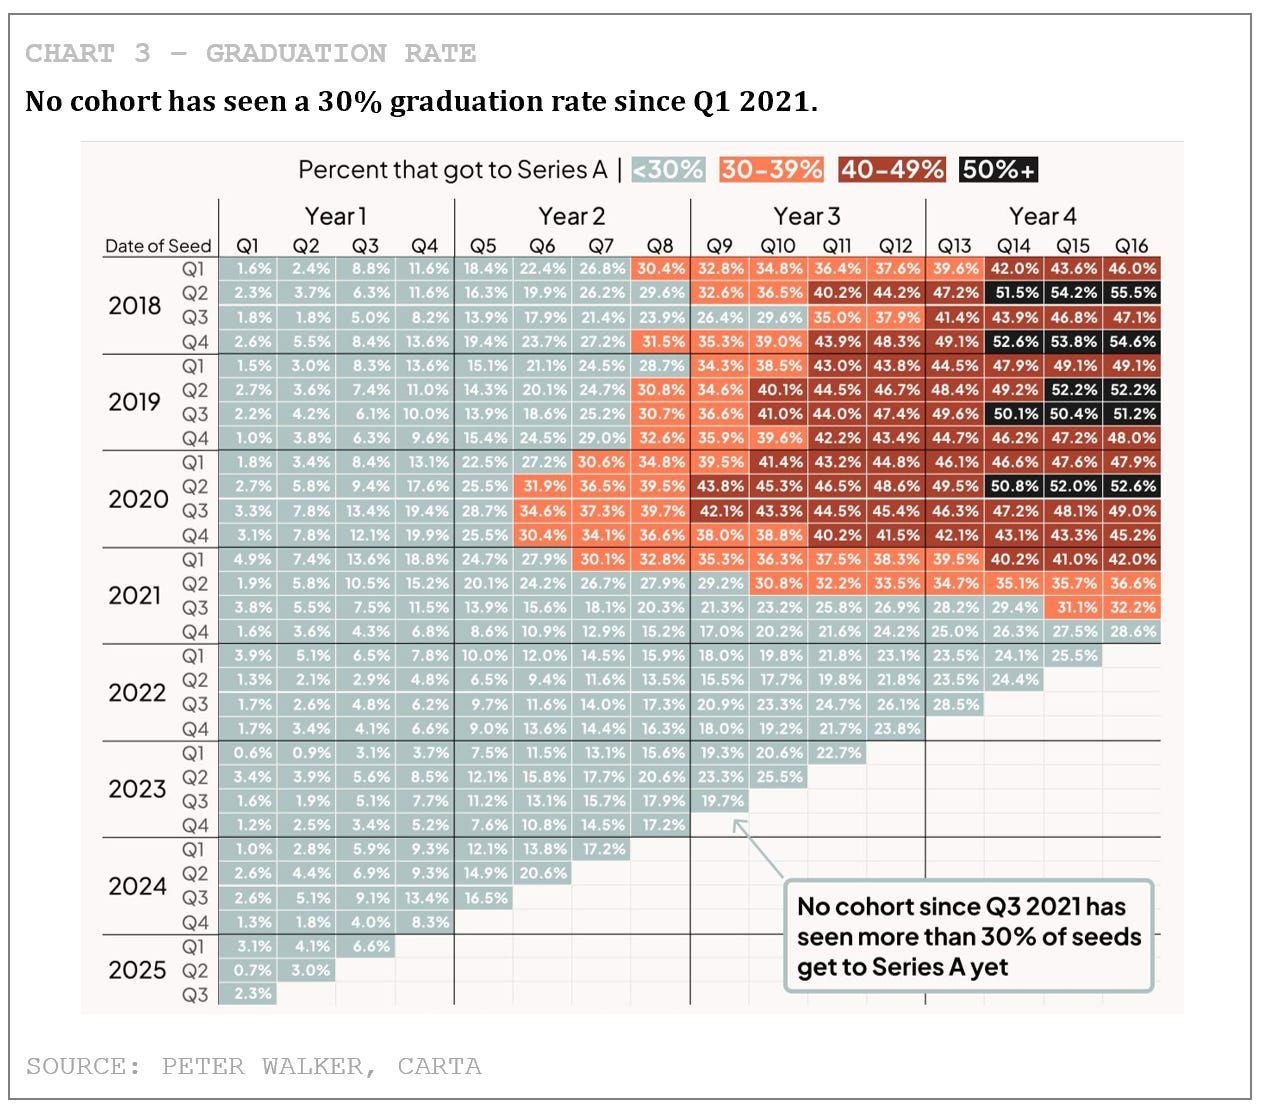
There are caveats. Some founders are choosing to seed-strap, and some cohorts still need more time to mature.
The problem is that the stories people hear most often are the AI companies raising quickly and moving through rounds at speed. Those companies are real, they are just not the median.
A few companies are still moving through the stages quickly, but most are not. They are taking longer between rounds, raising extensions, cutting burn, or finding that the next round is harder to raise than they expected.
Two things stand out to me.
First, if you are two years post-Seed without a Series A, you are not unusual. That is now the position most Seed-backed companies find themselves in.
Second, the year you raised matters. It was much harder to graduate in 2022 and 2023 than in 2020. I have seen strong businesses get stuck partly because of when they came back to market. That does not mean every company should have raised, but timing clearly made the bar harder to clear.
The bridge to somewhere, hopefully
Bridge rounds have become part of the furniture. In the US, roughly 40% of all seed-stage investment is now bridge or extension activity, up from around 20% pre-2022. The UK picture appears directionally similar.
Chart 4 – Bridge round prevalence
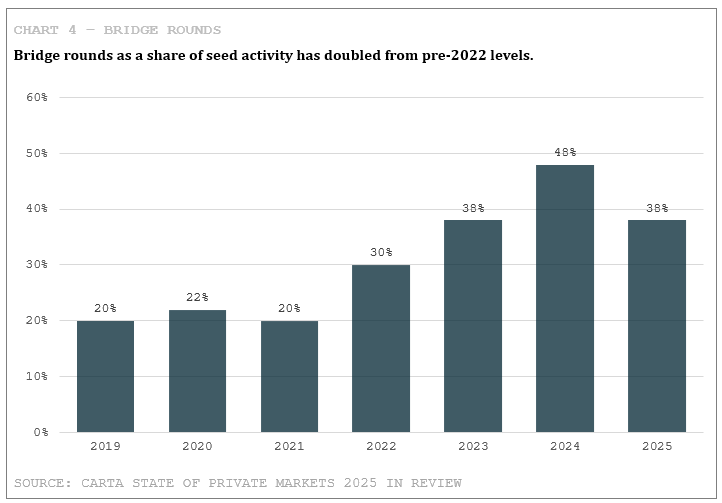
A bridge buys time. It extends runway and gives a company the chance to hit a milestone before going back to market. It can also delay the harder question of whether the company is still on the venture track at all.
Not all bridges are warning signs. Some of the best companies I have seen have raised them to launch in a new geography, release a new product, or deliver on a major contract before raising properly. Others use a bridge to avoid raising at a valuation they think is too low, which can be perfectly rational.
But when bridge activity is this high across the market, it usually means something has stalled. It points to a large group of companies that have not quite progressed enough to raise properly, extending runway while they wait for conditions to improve. A bridge used to be about reaching a clear milestone, but now it can also be a way to buy time while everyone works out what comes next.
What this means
The simplest way I’d describe the market is this: the recovery is real, but it is not evenly distributed.
At the top, a narrow group of companies are raising quickly, often at high valuations and with competitive term sheets. Some of those companies will justify the prices being paid.
Underneath that, deal count is weak, graduation rates are low, bridge rounds are common, and a large cohort of 2020–2022 companies are now in their fourth or fifth year post-raise. Many are caught between the market they raised in and the market they now need to graduate into.
The headline numbers do not tell you much about your own situation. For that, the questions are more specific: how long has it been since your last round, how fast are you growing, is that growth efficient, and would today’s investors realistically lead your next round?
Some companies are still clearly on the venture track. Some are good businesses, but probably not venture-scale outcomes. And some are still alive, but mostly buying time.
Sources
PitchBook Q1 2026 European Venture Report
Carta State of Private Markets 2025 in Review
PitchBook/NVCA Q4 2025 Venture Monitor
Atomico State of European Tech 2025
UK Venture Financial Returns 2025