

A consumer app renaissance?
It’s probably worth saying upfront that I’ve historically been very bullish on consumer. I’ve always thought it’s been underloved by VCs, despite the fact that many of the strongest European outcomes over the last decade have been consumer-led. Companies like King, Vinted, Spotify and others created enormous value by building products that reached massive audiences, often by riding the mobile wave particularly well.
Against that backdrop, for a while now, I have had a working thesis that AI would usher in a new phase for consumer applications. That belief was driven by two fairly simple ideas. The first was that the bar to creating and shipping apps would drop dramatically. AI code generation would make it possible for non-developers to build and release apps, while also allowing experienced developers to move faster, test ideas more cheaply, and ship more often.
The second, and more interesting from my perspective, was that LLMs would unlock entirely new types of consumer applications. Not just slightly better versions of existing products, but apps that could solve problems in ways that were previously hard or impractical. Things like booking holidays end to end, genuinely useful AI personal assistants, real-time restaurant recommendations, or personalised financial advice that actually adapts to the individual rather than just surfacing generic insights.
At a high level, parts of this thesis are clearly playing out.
The noise doesn’t lie
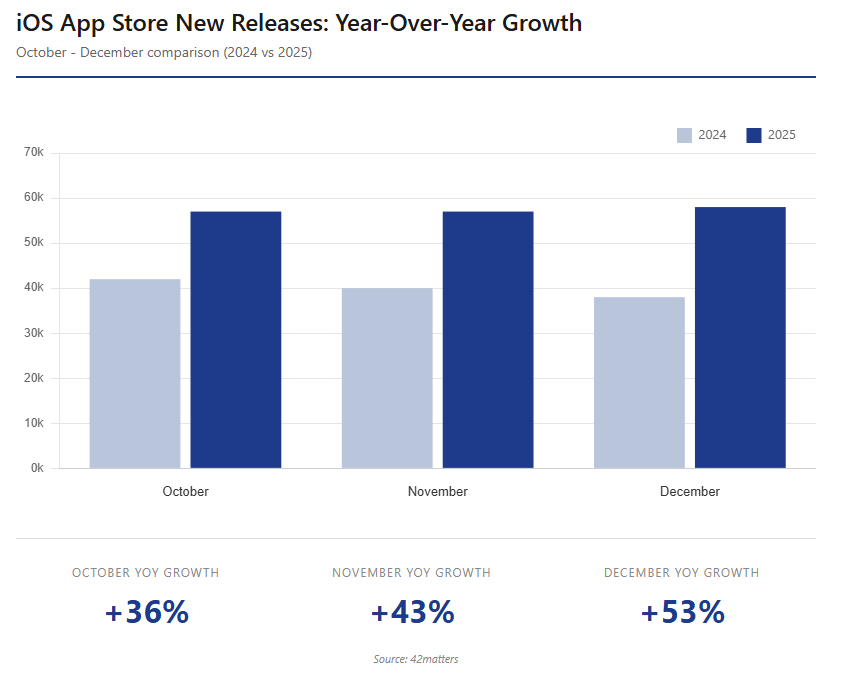
We have seen a meaningful increase in the number of new apps hitting the App Store year over year, roughly lining up with the adoption of agentic coding tools starting in early 2025. At the same time, a wave of platforms has emerged specifically to help people build consumer apps. Tools like Rork, VibeCodeApp, and Wabi are explicitly focused on this use case. Even more established platforms like Replit have recently launched tooling designed to make consumer app creation and App Store deployment much easier.
Distribution has also shifted in a noticeable way. Video-first platforms like TikTok have been flooded with both human and AI-generated UGC promoting new consumer apps at huge scale. One particularly interesting example was an AI-generated monk with over a million followers, which delivers wisdom and life advice. Funnily enough, it’s also being used as a funnel to sell a 30 day wellness course. Although not app specific, this feels like a fairly good illustration of how far things have moved from traditional consumer marketing playbooks.
Or does it?
Given all of that, I expected to see more movement at the top of the charts than we actually have.
Looking at US app usage data by demographic as of Q4 2025, the picture is remarkably stable. Across every age group, the top ten is dominated by the same names that would have appeared five years ago: YouTube, Instagram, Spotify, Amazon, Facebook, WhatsApp, TikTok, Discord. YouTube sits at number one for every cohort from 18 to 55+. The generational differences that do exist, like Discord ranking higher for younger users or Messenger rising with age, are shifts that were already underway before the current AI wave.
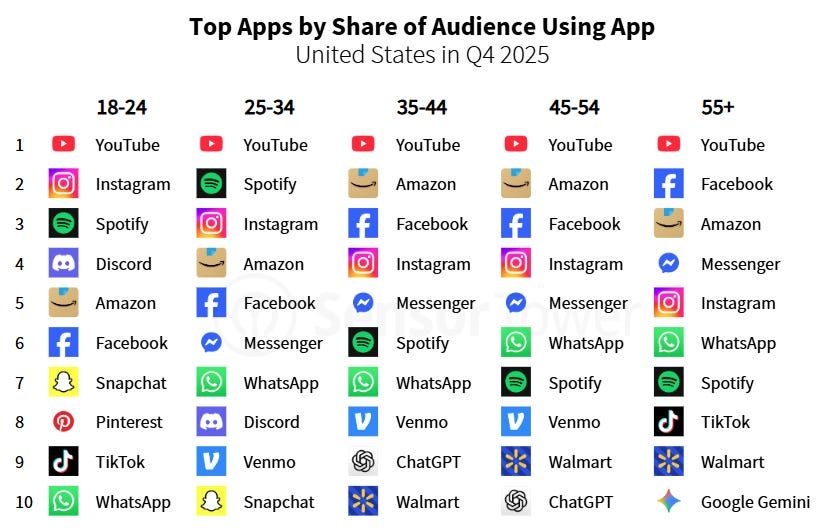
The only AI-native apps to appear anywhere in these rankings are ChatGPT and Google Gemini, and even then only in a handful of slots. One thing I did have to sanity-check when looking at this data was whether I was missing something obvious. These are new, AI-native platform companies sitting inside the top ten. In that sense, it’s hard to argue that AI isn’t already winning at consumer scale.
The distinction I’ve found useful, though, is between foundation model companies with consumer apps and consumer application companies themselves. These products aren’t really competing inside the same dynamics that most consumer app founders are operating within. They are horizontal platforms with massive capital, brand, and model ownership behind them, and their apps are better thought of as interfaces to infrastructure rather than standalone consumer businesses. Their success tells us a lot about consumer demand for AI, but much less about whether the structure of opportunity has changed for new consumer app companies.
Beyond that, the list is dominated by long-established companies across commerce, social, media, and utilities. The incumbents haven’t just held their ground. They’ve barely had to move.
Where things do start to look different is when you drop down a level and look at specific categories rather than the charts as a whole. In education, several of the top free apps are now AI-native, covering use cases like flashcards, English learning, and even plant identification. In health and fitness, AI calorie trackers have started to show up. In photo and video, AI is effectively everywhere. Seven of the top 20 free apps are AI-native, and even historically non-AI apps have aggressively rebranded themselves around AI, with names like “Canva AI Photo & Video Editor” or “Adobe Express: AI photo, video”.
These are categories where AI offers a very obvious, immediate improvement to the core experience. Outside of them, leadership has been far more stable. Even where new apps do break through, many are still relatively thin wrappers around foundation models, and the usual forces of distribution, brand, and habit continue to dominate outcomes.
Consumer apps have been on a tear
One piece of context that I think is easy to miss in all of this is that consumer apps have already been through a massive growth cycle. Over the last ten years, non-gaming consumer app revenue has grown dramatically, steadily expanding from 2016 onwards and overtaking mobile gaming revenue in 2025. That is not what an early or underdeveloped market looks like. It is what a large, mature industry looks like.
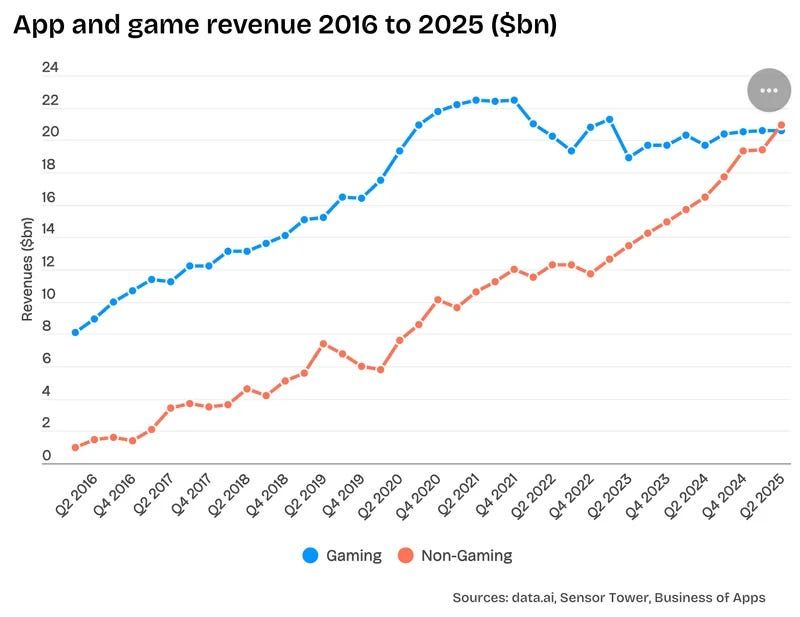
Seen through that lens, the current wave of AI tools is not landing in a greenfield market waiting to be unlocked. It is landing in a market that already works, already has entrenched winners, and already exhibits strong power-law dynamics. That makes it much easier to understand why a surge in app creation has not translated into a reshuffling of the charts. The consumer app “renaissance” already happened. What we are seeing now feels more like a new layer of experimentation being added on top of an existing, highly competitive ecosystem.
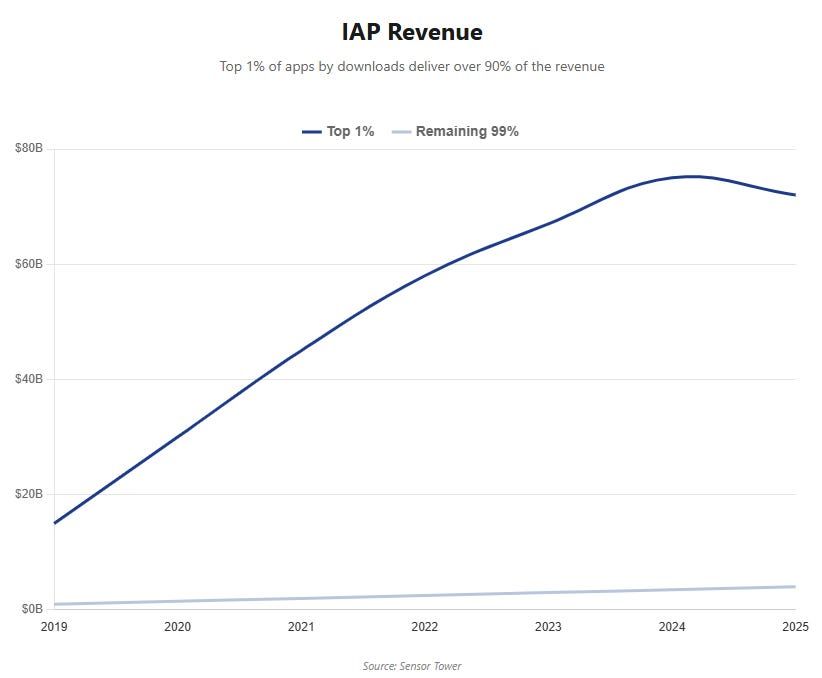
This is what has led me to a more measured view of the current AI-driven wave in consumer. AI feels much more like a supply multiplier than a reset of the market structure. It dramatically lowers the cost of experimentation and increases the number of apps being created, but it does not fundamentally change the distribution of outcomes. Consumer apps remain power-law driven, and breaking through is still hard. Sensor Tower’s data suggests that the top 1% of downloaded apps deliver over 90% of the IAP market total revenue.
That does not mean there are no opportunities. It just means they are narrower, and more specific, than the hype sometimes suggests.
Where is the opportunity?
I do expect a small number of genuinely strong AI-native consumer application companies to emerge over the next year or so. These will likely look quite different from the first wave, which often felt like quick experiments wrapping a foundation model around a single use case. The more interesting opportunities probably involve deeper consumer workflows. If I had to guess at categories, I would be looking most closely at personal finance, fitness products that adapt in real time based on health data, and potentially new forms of social interaction that are hard to predict in advance.
Distribution for these products is likely to be community and influencer-led rather than driven by PPC or SEO. That may increasingly favour founders with existing audiences and, over time, could lead to more apps being launched by creators or public figures rather than traditional startup teams.
I am also spending time thinking about what new AI-native infrastructure might emerge on the consumer side. Many of the traditional layers now feel mature or effectively wrapped up, particularly ads, attribution, analytics, and in-app payments. Where things get more interesting is in areas where AI is changing the shape of the product itself.
One related question I keep coming back to here is where inference actually lives over time. Today, most consumer AI apps are effectively thin clients on top of cloud-hosted models, which reinforces the advantage of companies that own the models, the infrastructure, and the unit economics underneath them. That setup makes it very hard for smaller teams to compete beyond being wrappers.
If more inference meaningfully moves on-device, that could start to change the shape of what’s possible at the application layer, particularly around personalisation, latency, privacy, and cost. It’s still early, and it’s not obvious how far this really goes in practice, but it’s one of the few technical shifts that could plausibly alter where value accrues in consumer AI over time, rather than just increasing the volume of apps being built.
A few areas I keep an eye on here include adaptive frontends that can restructure themselves per user rather than just personalising content, private or social deployment models for small or throwaway apps that are never meant to live in a public app store, and more agentic approaches to consumer support that can actually take actions inside a product rather than just respond to tickets. I am also interested in how intent-level payments might evolve as software agents start spending on behalf of users, and whether portable identity or memory layers could emerge that compound across apps rather than being rebuilt badly each time.
When infrastructure works in consumer, it tends to benefit from the expansion of an entire category rather than from any single breakout. RevenueCat’s growth alongside the rise of AI subscription apps, with OpenAI being the most visible example, is a good illustration of how that dynamic plays out in practice.
Recent shifts around app store policies and web-based payments don’t really change this dynamic. If anything, they tend to favour teams and platforms with enough scale to absorb complexity, which is part of why companies like RevenueCat are able to expand their footprint as the surface area of the app ecosystem grows.
Finally, I think app creation itself will increasingly become a hobby or creative outlet rather than a purely commercial activity. People will build small, disposable apps to share with friends, whether that is planning trips, running private bets, or organising small communities. Tools that make this kind of social, private deployment easy may do well because users are paying for enjoyment rather than return on investment. In that context, Wabi’s positioning makes sense to me. By contrast, I am more sceptical of platforms focused purely on shipping apps to traditional app stores in their current form. Over time, many people will realise how hard it is to build something commercially meaningful in a mature market.
Overall, it does feel like AI has brought a lot more energy back into consumer, which the space probably needed. There’s clearly more experimentation happening, and the mechanics of building and distributing apps have changed quite a bit. But when you look at where value actually ends up, things don’t feel radically different.
Distribution has shifted away from PPC and SEO towards influencers, UGC and communities, but the outcomes still look familiar. A small number of companies capture most of the value, and for most apps it’s still very hard to break through in a meaningful way.
So consumer apps don’t really feel like they’re at the start of something new. They feel like a mature market going through another phase. AI isn’t restarting the story, but it is changing how the next part of it gets written, and I think that’s probably the right way to think about what’s happening.