

Vibe Check
Since Opus 4.5 dropped at the end of November there’s been a clear proclamation from silicon valley insiders that Claude Code is starting to get really, really good.

Compounded by weekend captivation’s with Moltbolt and Moltbook, the whispers of fast take off have started. With the vibe shift markets are getting twitchy, simultaneously punishing Microsoft for excessive AI capex & Open AI RPO exposure while rerating the entire software ecosystem indiscriminately at Anthropics latest product release. Go figure.
So naturally the FOMO grows: am I drifting into the technological underclass or is much of this just performative? To date I’ve err’ed towards the latter. Vibe coding ephemeral pieces of software once or twice with Replit / Lovable is cool. My most successful project to date was replicating something akin to FrontPage.com in a bid to diversify my news sources, neat at first but the data integrations soon broke and maintaining it was a bore. Perhaps I’m creativity constrained, but honestly in most cases I’d rather just pay for the real thing and not have to maintain it.
But this weekend I found some genuinely useful examples where, despite my technical limitations, Claude Code enabled me to go deeper into research and analysis. I’ll caveat this was 90 mins of work on a Sunday prior to depleting my tokens, but for data analysis and visualisation of large or hard-to-aggregate datasets, it proved invaluable. A civilians attempt at Claude Code.
Exhibit A: Flat Hunting
Now admittedly this whole analysis is cope faced with the prospect of anemic London property growth, but like any ex banker I love some comps. Normally I’d be faced with the prospect of combing Rightmove’s recently sold tab for a quick sense check, but one context dump into Claude Code and finding, scraping and visualising data is very intuitive, even for a technical luddite like myself
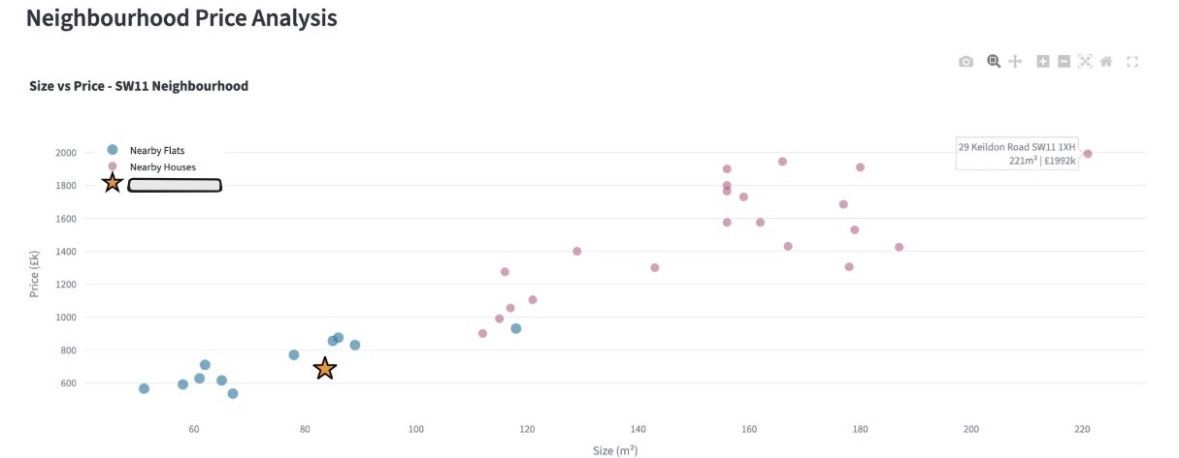
In my case we(?) landed on HouseMetric’s as an interesting data source and with a few tweaks I had the above interactive visualisation with comps per SQM pulled for the street of the target property and selected surrounding area. From here it was fairly simple for Claude to output a basic financial model to get a feel for an IRR based on varying investment assumptions like mortgage costs, stamp duty, reaching SQM price parity with the area etc. Now at least I can negotiate with some source of truth and all within half an hour.
Exhibit B: Student Loans
Next, I turned by attention to the topic du jour in the group chat, as late-twentysomethings begin to grok how interest works. For the uninitiated, the central point of contention is that for high earners on Plan 2 loans, the RPI + 3% interest rate borders on usury and is explicitly structured so higher-earning graduates subsidise those who cannot fully repay their loans.
The addition of a real interest rate is intended to make the funding system more progressive, so higher earners make more of a contribution to the costs of higher education than lower earners. This practice was adopted for plan 2 loans following a review of higher education funding in 2010, known as the Browne Review. This review recommended graduates should pay for their higher education in proportion to the financial benefit they have received. Charging a real interest rate on loans also reduces the public subsidy for higher education from the taxpayer, making the student loans system cheaper than it would otherwise be for the government. – UK Parliament website
Most graduates can likely reconcile this cross-subsidisation when it supports degrees with high social value (nurses, allied healthcare professionals, teachers). There is far less sympathy for market-facing degrees, where economic outcomes vary widely by institution. Put plainly, weaker universities producing low-return credentials. Does this variance actually exists, and if so, how large it is?
Well, the UK government publishes the Longitudinal Education Outcomes (LEO) dataset, which links education records to HMRC tax and DWP benefits data to show realised graduate earnings. It’s sizable, around 187,000 rows in the main subject dataset, covering 300+ institutions and 38 variables.
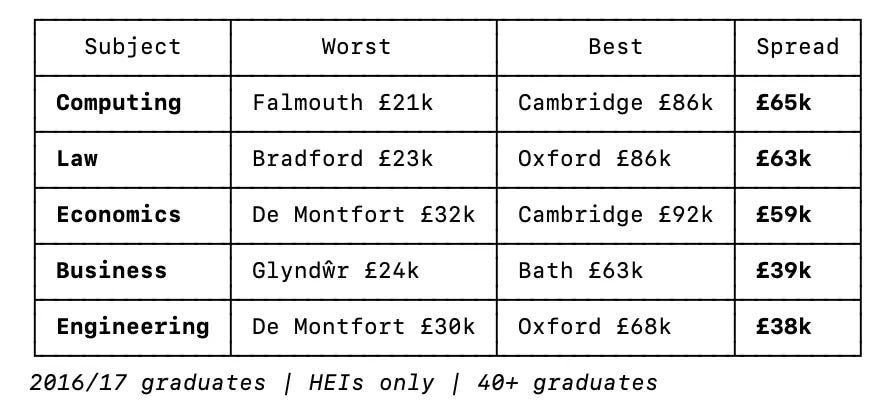
This is where Claude Code gets fun. I don’t write Python and would normally avoid Sunday morning data analysis, but after roughly 20 minutes of talking to my laptop, some useful insights emerged. For what follows, I focused on 2016/17 graduates, five years post-graduation, with a minimum cohort size of 40 (which, notably, excludes Oxford in business). Unsurprisingly, variance of outcomes on market facing degrees (economics, law, computing etc.) are stark.
From there, Claude decided on £41.5k 5 years post graduation as a rough proxy for whether a graduate is “net subsidised” (i.e., unlikely to repay in full) or “net contributor” (i.e., likely to repay and cross-subsidise others). The level is debatable — my interest-rate assumptions are crude — so treat it as directional rather than precise. What’s striking is how little underwriting logic exists in the UK system. A normal lender would price risk, cap exposure, or apply heuristics about the quality of the underlying asset by discipline and institution. This quite clearly is not the case when it comes to UK student loans, making it a particularly tough pitch when you’re asking graduates to chin RPI + 3% to subsidise swaths of market facing degrees with negative NPV. Perhaps we could at least consider nuance. Take Australia, who use a variable co-payment system based on the degree you’re studying.
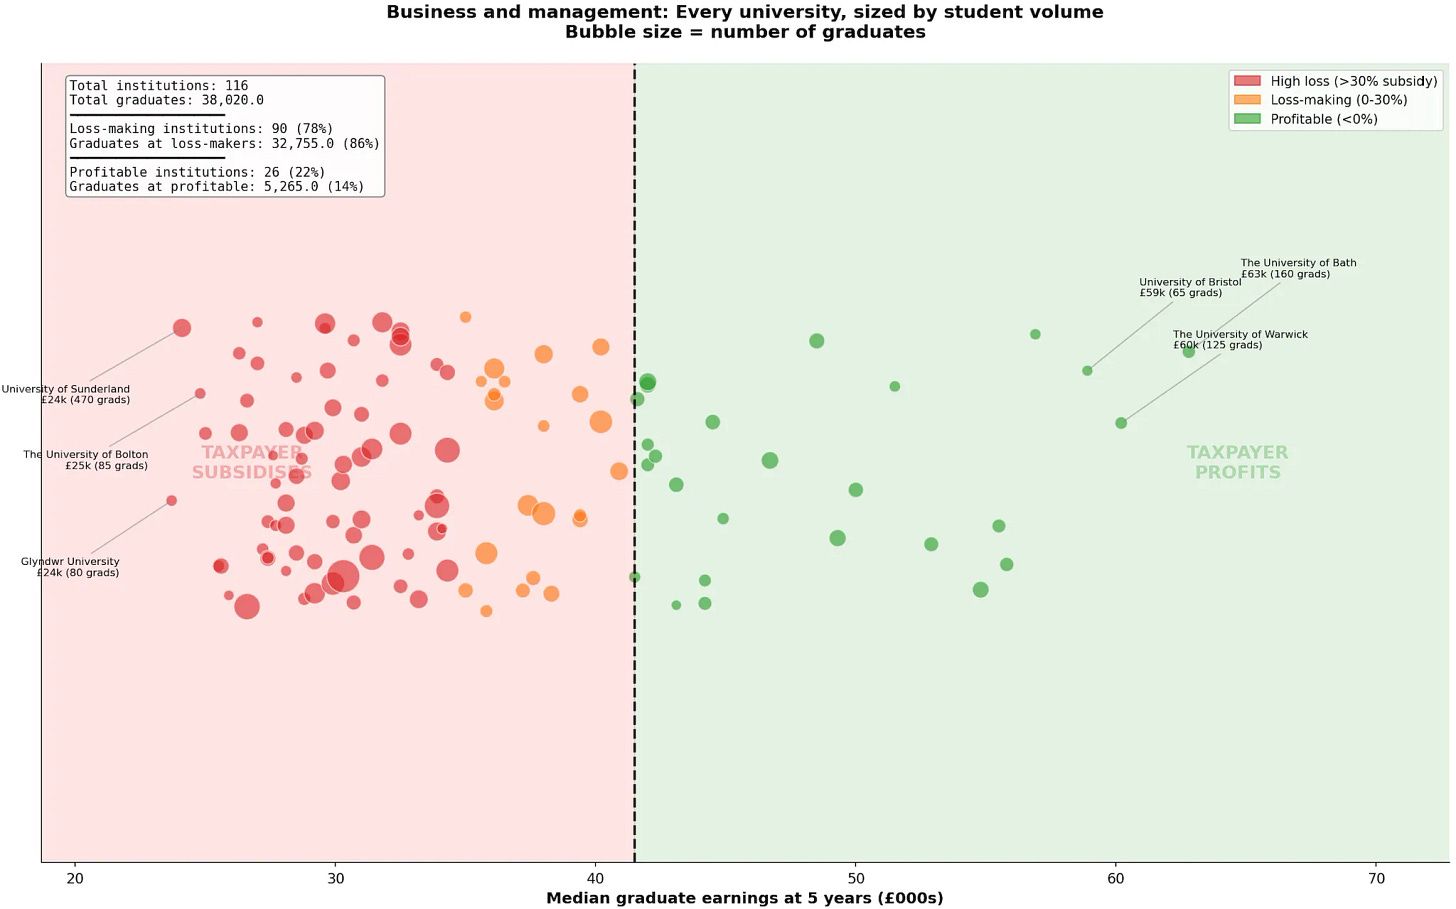
Looking at the variance, the obvious question is why the market hasn’t self-corrected. Who is incentivised to keep this bus rolling? Near-term governments benefit from higher participation: lower measured unemployment, a ready-made “equal opportunity” narrative, and (in many swing seats) universities that function as anchor employers, sustaining second-order local economies in places hollowed out by deindustrialisation. That may be politically rational, but it’s less clear why high-earning graduates should be the ones picking up the RPI + 3% tab
Student Loan Factories
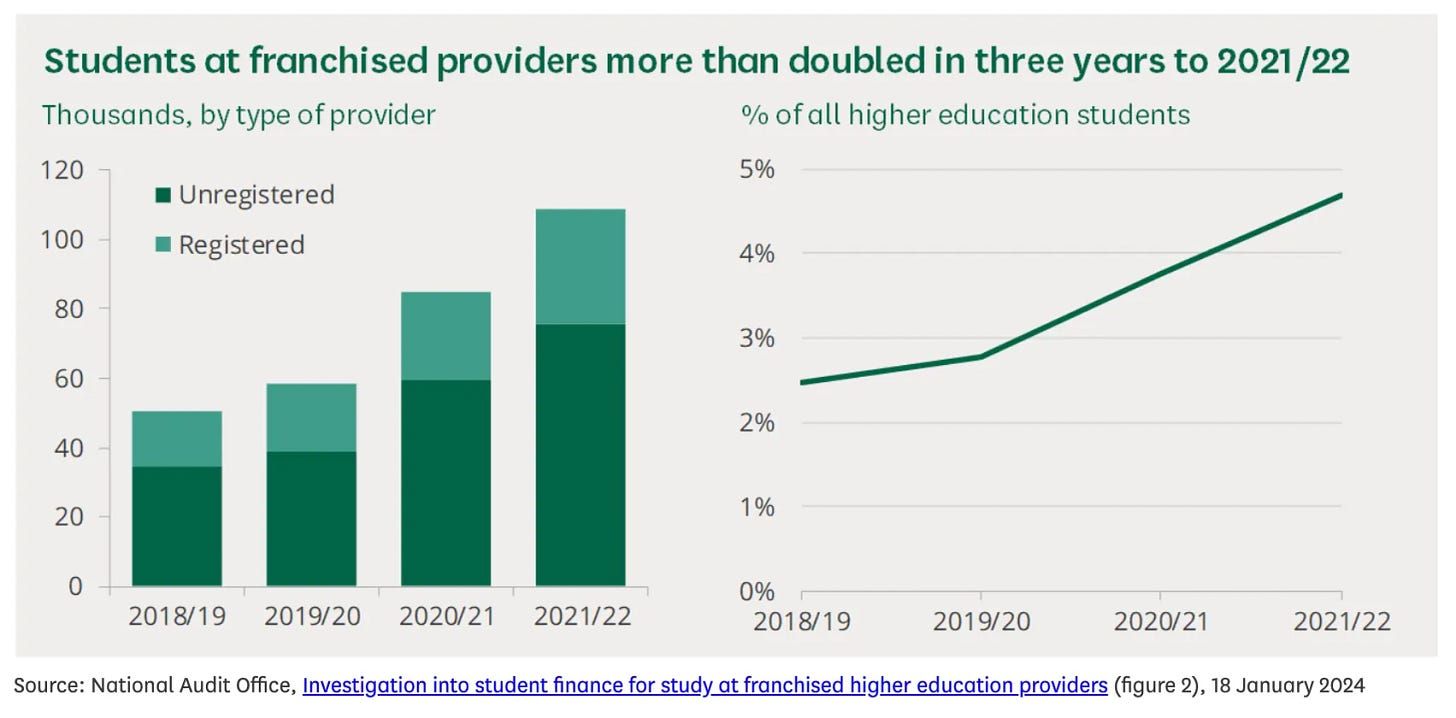
Things got more interesting when Claude Code pointed me to a 2024 government report on student loan fraud in franchise universities. Universities can enter a franchise partnership with another educational provider, students enroll with the lead provider (the university) and assuming they’re OfS registered can claim for student loans via the Student Loans Company. The universities then pass on this revenue to the franchise partner, taking a cut for their troubles.
Nick Shirley has already shown the way in the US unearthing the Somali daycare centres fiasco and the BMJ recently flagged Birmingham’s questionable overseas doctors training scheme. YC even have Infra for Government Fraud Hunters in their latest request for start-ups. It seems one might have fertile ground in the UK student loans ecosystem. Per the National Audit Office:
“in the academic year 2022/23, only 6.5% of students receiving student loans were studying at franchised providers. However, 45% of all student loan applications suspected of fraud were for franchised providers”.
For context, the Office For Students highlights there are now c.140k such students, 62% of which are doing market facing degrees like business management and 65% of which do not have English as their primary language (although apparently a duolingo streak will suffice)
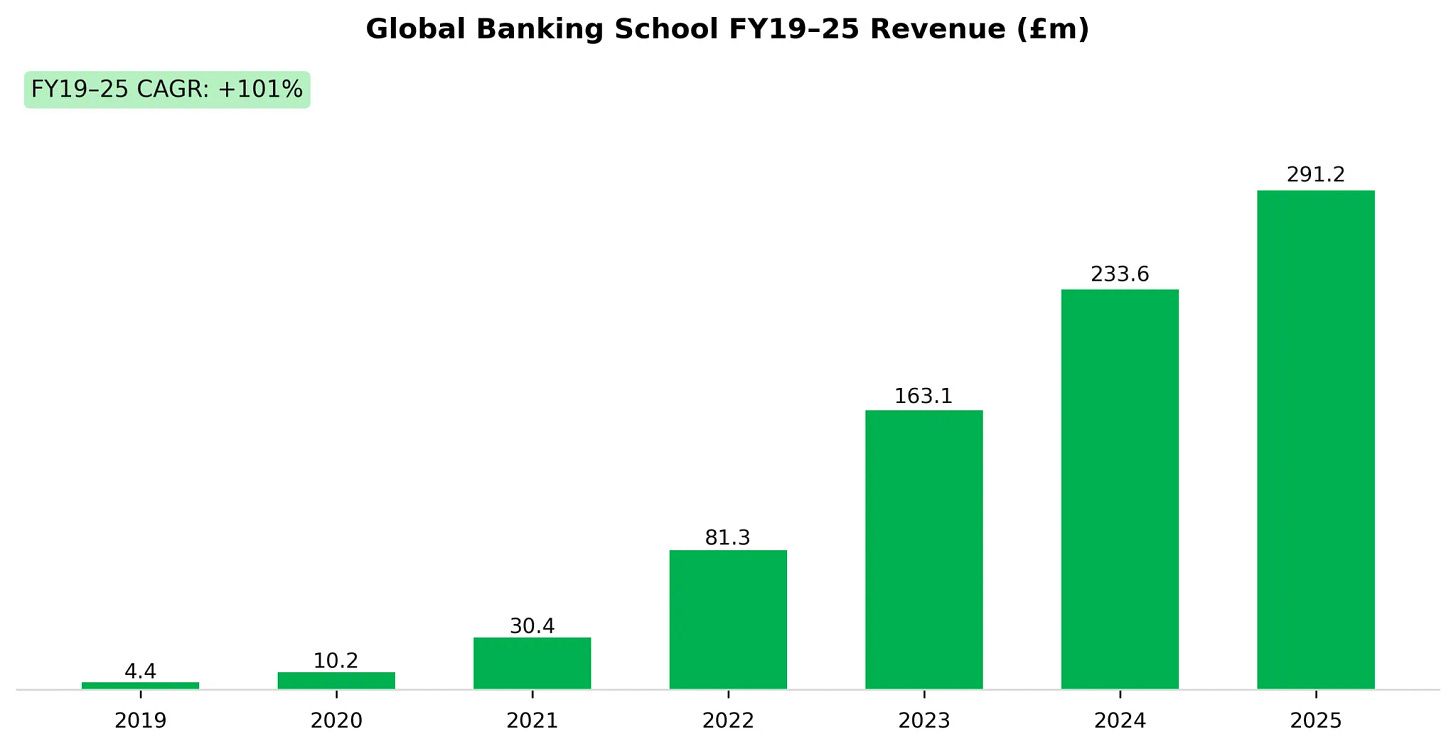
As my last hurrah before retreating to the pub I landed on Global Banking School, which Claude sycophantically described as The Franchise Model on Steroids. Oddly I do not recall any of my former banking colleagues having attended. Alas others appear to have clocked their genius already, but its worth the pause. They started life in 2010 doing finance training courses and in 2016 open their first campus in East London. GBS have now rapidly expanded under the franchise model partnering with Bath Spa University, Oxford Brookes University, University of Suffolk, Canterbury Christ Church University who reportedly get a 25% kick back. Linking Claude Code to the Company’s House API and one-shotting a BCG Analyst, it appears growth’s not been too shabby. Not to mention £54m of dividends paid up to the holdco in the last 2 years. Chef’s kiss.
If you’re squirming under an RPI + 3% loan and are interested in tackling government fraud & inefficiency through the medium of start-ups, I too request Infra for Government Fraud Hunters. Get in touch on Jamie@triplepoint.vc