

The Lay-up to 2026
- The VC industrial complex is rotating into Productive Capitalism, and the markets are making a concentrated bet on the AI boom. As a result, technology is becoming more political than ever, especially when Trump wants all time highs (& Greenland?) to celebrate America’s 250th birthday in July
- There’s an element of technological determinism at play here, once infrastructure is built, capital deployed and incentives set certain trajectories become inevitable. The future is coming, so position accordingly
- Of course, there are timing arguments. Gavin Baker summed this up nicely in November reflecting on the Gemini 3 release. The bull case still has legs, Gemini demonstrated there’s juice left in pretraining, and with the first Blackwell clusters coming online, the race to be the lowest-cost producer of FLOPS / tokens continues to accelerate with all eyes on xAI in H1’26. But the near-term risks remain of an ROI air gap emerging and depreciation schedules coming into sharper focus. This explains the fascination with CH Robinson’s earnings, any evidence of AI driven, measurable productivity gains stand to get shilled. But however impressive the automated scheduling capabilities of a 120 y/o freight broker are, the street needs more to keep the bus rolling in 2026
- Tesla is living proof that narratives can outweigh fundamentals, even in public markets. Cast doubt on their EV positioning as BYD eats their lunch and I’ll raise you an autonomous robo-taxi fleet, cleaned by Optimus robots that will greet you at the spaceport. Investors like to feel intellectually dominant, they need new stories to counter the AI bears. Hence the large labs are aggressively targeting automating:
- Financial analysts: I get Mercor spam weekly and it makes sense. FA’s are the apex of the memetic wheel and gate keepers to the capital AI capex needs. Altman needs FA’s to feel the AGI, it seems logical they’ll be a correlation between sentiment my highly prestigious job is cooked and willingness to suspend disbelief on the AI supercycle.
- Discovery of novel science: Semianalysis recently dug into data collection for RL by big labs here. Hard to refute AI if we’re discovering new science, it just sounds smart … it gets the people going?
- But for founders and VC’s near-term blips are somewhat irrelevant, this is coming, so where to focus? Well, the FT’s word of the year for 2025 appears to be K-Shaped. We’re seeing bifurcation across wealth, education, health, venture funds etc. This of course is not AI’s doing, but does it accelerate or reverse some of these trends? The same technology that promises to trivialise your DCF also underpins the autonomous vehicles that reshape labor markets, creates the investor enthusiasm to drive towards energy abundance, accelerates VC capital concentration and fuels the trillionaires to chase their longevity dreams.
What I’m Thinking About in 2026
You’ll probably just summarise this in Claude, so I’ll try to keep things brief. These aren’t all specific investment theses, rather an observation on trends creating dislocations and therefore potential opportunities for founders to steer us towards a techno-optimistic future.
Financial Disillusionment
- This viral essay captured the vibe and Apollo’s update helps add some numbers to it. The social contract feels broken when the average age of a first time buyer in London was 35 last year. So some become degen’s playing prediction markets on Polymarket or perpetual futures on Hyperliquid, while others choose self-determination in the form of entrepreneurship or escapism in the form of social media slop,endurance sport, tattoos etc.
- This unease helps fuel the populist barbell: Greens / Mamdani point to wealth inequality, while MAGA / Reform cite immigration / welfare grift. The tech elites have got their messaging wrong around AI, extolling job replacement doesn’t win hearts and minds. With trends towards privatisation of returns, compounding leverage on capital vs labour and a proposed California wealth tax they’ll be a big narrative shift this year. More Michael Dell’s funding Trump accounts, or perhaps emulating the robber barons with research institutes and monuments. It all no doubt intensifies in the medium term once Elon’s a trillionaire and the insurgency swept Sahel region becomes less inhabitable.
- My belief is AI must inevitably result in some exacerbation in financial inequality, at least at the tails. Just watch the DeepMind documentary and tell me a 16 year old Demis with 1,000 Claude code agents would fail to have anything but extreme economic success. Rewards of self-directed learning and agency get amplified, but if we can get the GDP growth hopefully we’ll all be eating cake.
- Enabling upskilling, retraining, local businesses, entrepreneurship are all interesting places to be building
Energy Abundance
- These markets are obviously challenging for start-ups to directly influence, so perhaps best to channel your inner degen and ride the silver and copper spots? But, AI does create the impetus for markets to solve for energy abundance, energy = compute
- With the highest industrial energy prices in Europe and a reliance on China to keep our green blushes at bay, the UK is firmly on the wrong end of this K. As Rivan articulate well, heavy industry where energy is a key COGS (chemicals, steel etc.) is essentially economically unviable without government subsidy. Not exactly ideal if you’re fourth turning pilled
- For most of the world solar and storage seems to be the answer, however the UK’s geography & density isn’t quite so accommodating. At least we benefit from an abundance of wind, despite the lack of transmission infrastructure to prevent curtailing it. One must then grapple the own goals of decimating our nuclear learning curve, gas storage and the general dysfunction of infrastructure projects.
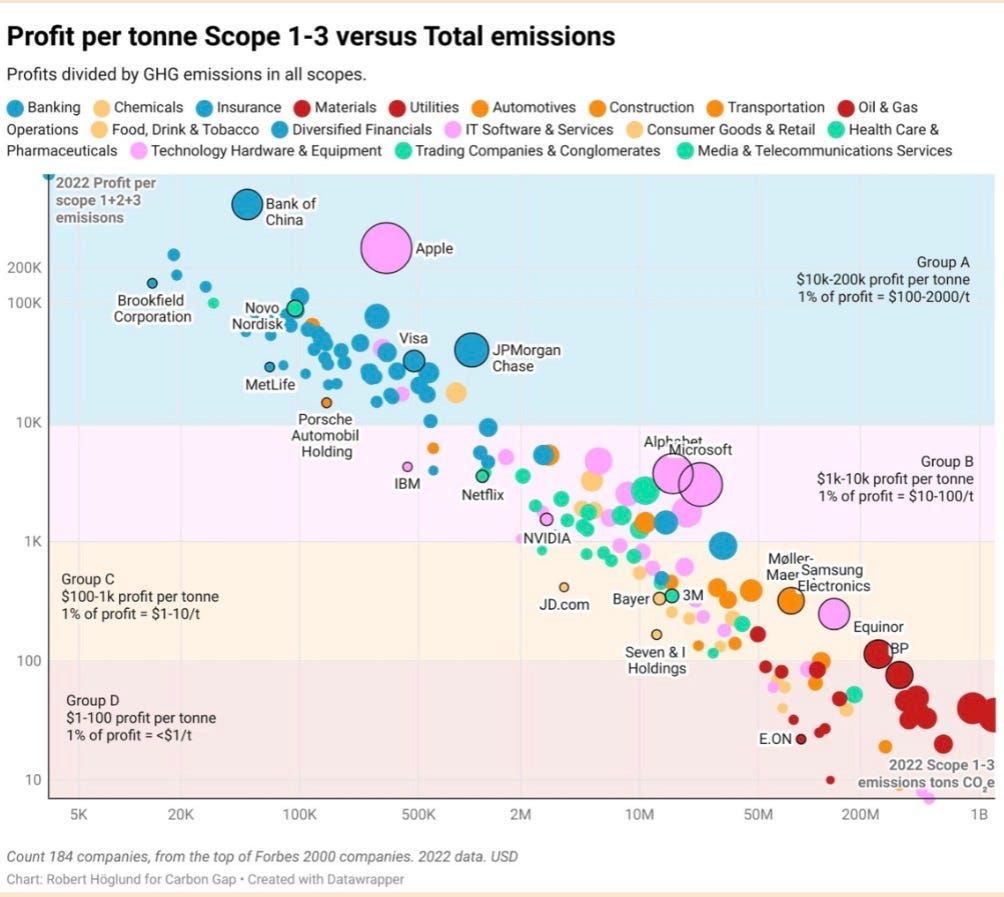
- But if you squint your eyes and whisper clean beautiful coal, what does energy abundance enable? Well helpful for those most levered to the cost of energy per below and for those seeking to transform heavy industries like chemical production, water desalination, metal processing etc.
- As progress toward energy abundance advances, much of this action may happen outside the grid, particularly relevant in the UK where renewable subsidies, transmission costs etc.lock in long-term inflated energy prices. We’ve already seen xAI’s Memphis data center installing 550MW of onsite gas peakers rather than connecting to the grid, and now start-ups emerging to accelerate this. Increasingly important in the populist backdrop with AI spiking local energy prices
Longevity & GLPs
- Skinny’s a commodity in a pill now, so what’s the next status symbol? Ah yes, you’re on the wolverine stack, but what do you mean you still use a Teflon pan, haven’t you heard of PFAS? Interesting, well I’ve got the SIK3 mutation so I’ll read up about that tonight while you have to sleep. Oh nice, but good luck being top decile for nighttime erections.
- We’re in the midst of a healthcare mean reversion. The historical arc began with self-management through folk knowledge and community healers. Apothecaries and early physicians formalised knowledge, which rolled into early medical institutions like convents & monestaries. As 19th–20th century innovations created technological dependency, our modern hospitals emerged resulting in our centralised, reactive, episodic medical model.
- Advances in diagnostics, biosensors, AI triage, remote decision-support and democratisation of knowledge via LLMs may create the lay-up for more self-managed care. Success of players like HeliosX, Eucalyptus, Hims etc. and the general longevity / aesthetic boom is testament to increased willingness to self-pay and self-manage one’s health. So how would one index this? Belsky points to $DGX & $LH and insurance disruption. And with self-pay comes consumer marketing, which has drawn scrutiny across the US, China and the UK. More plays rhyming with Solstice Health, AcuityMD, Full Script,Roon,Keychain etc. I am sure.
- In Titanium Noir, T7 therapy provides elites with effective immortality but at the cost of growing physically larger. It’s an interesting framing when already at the very tails of US society there can be 15 year life span differentials, some K. If we don’t die should I be investing on a 120 year time horizon? If only Buffet had another 30 years of compounding. Paired with BCI’s and artificial wombs, how does that change the decisions of god kings like Putin, Trump or Xi? Certainly not the obvious lay-up for reducing wealth inequality
- I’ll skip the classic aging population trope,it’s important but slow moving. Dan Wang’s observation was interesting. With advanced technology does this even matter to industrial progress? Just look at South Korea, their demographic data is simply depressing but their electronics industry is ripping with the Kospi up 76% in 2025
Autonomous Vehicles
- You can tell when somebody has visited SF or Austin by their instagram story. Waymo has already flipped Lyft in SF and the keen eyed will have spotted them gearing up for a London launch. Likewise Uber is progressing with Wayve and Chinese Baidu (?)
- So what does this change? Is there anything that FSD makes economically viable that previously could not exist? Real estate and insurance repricings, reduction in collisions and increases in recalibrations, do remittance players need to hope Uber drivers are really going to become data labellers, long Hertz to win the logistics orchestration?
- FSD is the bellwether for broader robotics disruption, the foundations of which attracted so much VC investment in 2025. I’ve previously written about the opportunities to turn opex into capex for robotic-enabled services, but it will be fascinating to watch what breaks and the second order opportunities created. All eyes will be on Amazon as first mover at scale and extending the auto analogy, who becomes the CCC, Copart, Bumper, Steer etc.?
- Growing up in more rural England, I reflect on my Mum’s relatively insane 3 hour daily driving commute for her job in the NHS, bookended by the school run, then only to earn the privilege of ferrying us to sports and social commitments on the weekend. Anything that makes being a parent easier must be a positive?
Counter Positioning The VC Industrial Complex
- Venture is bifurcating, smaller early stage boutiques and the mega funds. I’ve written previously about how this can result in misaligned incentives at the early stage and undoubtedly we’re seeing it result in the sort of target herding also seen in bio. Only certain markets are obviously legible to the TAM heuristics of mega funds and as AI content explodes (pls Pangram me) we’re increasingly reliant on algorithmically filtered feeds which perpetuate group think in an industry which undergoes truly rapid species evolution towards anything signalling traction
- For smaller funds, does this create a dislocation and alpha in overlooked markets, now not deemed ambitious enough? The tweet below is a completely rational heuristic investing from a $1bn+ fund, but says the quiet bit out loud. With our mandate we’ll do plenty well putting future $100m ARR company’s in business and if they’re now going to be lower competition I’d willingly forgo the status games of venture. Follow-on funding is a manageable risk, if you can show a 30%+ IRR capital will be available and while undoubtedly the right series A fund can help accelerate your business, with the leverage AI now creates unless you’re in a category getting king made, underwriting to a series A doesn’t have to be the default. This year we’ve seen a couple companies in the portfolio go from 0 – c.$2m revenues and close in on profitability from relatively modest inception rounds. If you’re not capital constrained, why raise?

- What are the interesting opportunities that start illegible to big venture on crude TAM maths? That look too small, too weird, or too operationally complex in a spreadsheet. One trend is founders taking a portfolio approach to these niches, building out from a common substrate like we’ve seen in tele–health, specialty insurance, media, consumer apps and with founders in lending, data businesses and roll-ups. It riffs off Rippling and having a knack for hiring ex-founders. This isn’t about being less ambitious or underwriting a triple backflip, but finding illegible platforms that can compound in ways that don’t show up in year-one TAM math. Perhaps many of these in EU will be enabled by lower localisation barriers previously mentioned. We’ve got some ideas for founders interested.
If you made it this far, I’d love to chat. Jamie@triplepoint.vc